

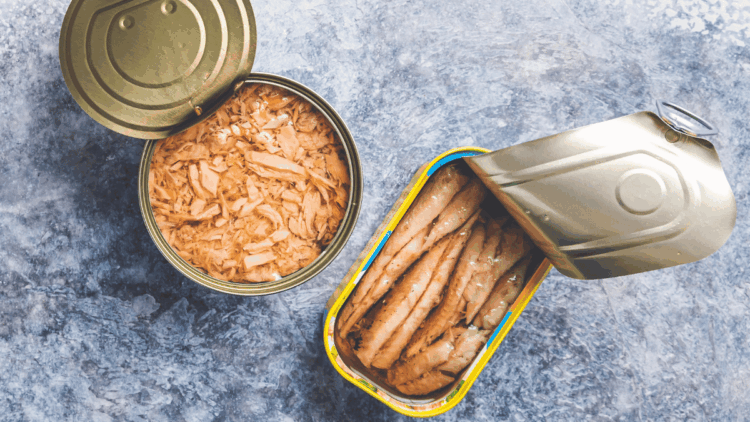
In 2025, canned tuna generated €1.683 billion, accounting for 82.4% of the Italian preserved seafood market by value, according to ANCIT. A 2026 Nextplora survey found that 62% of respondents reported eating canned mackerel, compared with 95% for canned tuna. The sales gap is substantial, yet mackerel still has a sizeable consumer base.

A last-minute pasta dish, a salad or a sandwich. When ready-to-eat fish is needed, canned tuna is often the first thing that comes to mind.
Canned mackerel has also been part of Italy’s seafood preserving tradition for generations. It shares tuna’s convenience and many of its eating occasions, but occupies a much smaller commercial space.
How wide is the gap? And what do the figures tell us about purchasing habits?
Tuna dominates sales, while mackerel retains its audience
In 2025, Italy’s preserved seafood market reached €2.043 billion, up 2.15% on the previous year.
According to ANCIT calculations based on Istat data, canned tuna alone was worth €1.683 billion, an increase of 2%. Tuna therefore accounted for more than eight out of every ten euros of the category’s total value.
The remaining €360 million covered mackerel, anchovies, sardines and other preserved seafood. These figures confirm tuna’s leadership, but do not allow mackerel’s individual share to be identified.
More recent evidence reinforces this picture. An analysis published by Food on 28 September 2026, covering the latest available 52-week period, put tuna at more than 90% of sales value within the tuna-and-mackerel market examined. Mackerel sales were broadly stable in value, with a slight decline in volume.
The two datasets cover different market categories, but both show sales heavily concentrated in tuna.
How many people eat mackerel, and how often?
The survey published by Nextplora in May 2026 adds another perspective: 95% of respondents said they ate canned tuna, while 62% reported eating mackerel.
The gap is significant, but it also shows that mackerel is familiar to, and consumed by, a substantial share of respondents. The percentages are not mutually exclusive: the same person may eat both.
Consumption frequency could help explain their different sales performance.
According to Nextplora, 77% of tuna consumers said they ate it at least once a week: 28% several times and 49% once.
The survey’s public summary does not provide an equivalent measure for mackerel. This distinction matters: the share of people who consume a product tells us how widely it is eaten, while purchase frequency and quantities help determine sales volumes.
A food eaten occasionally can have a broad consumer base without reaching the sales volumes of one bought regularly.
Flavour, pack formats and promotions shape purchasing choices
Tuna’s success is accompanied by a varied product range serving different eating occasions: traditional cans, fillets in glass jars, multipacks and tuna packed in water or brine.
Nextplora’s survey highlights a preference for multipacks: 45% of respondents chose packs of three cans, while 38% preferred family packs.
When choosing tuna, 64% considered flavour very important, 59% fish quality and 47% promotions. Fish origin followed at 42%, and price at 37%.
According to Food’s September 2026 analysis, stronger promotional activity and a lower average price per kilogram helped support sales in the tuna-and-mackerel category. This does not mean that both products recorded volume growth: mackerel volumes declined slightly.
For mackerel, there were also encouraging signs in private label. A second Food analysis published that month highlighted the positive performance of private-label preserved mackerel.
These are useful indicators, but explaining the gap with tuna would require comparable data on repeat purchasing, the number of products available, prices and promotions for both.
How much comes down to consumer preference, and how much to the products available on the shelf? That remains an open question.
Inside the can: differences in flavour, nutrition and origin
Tuna and mackerel belong to the Scombridae family, but have different characteristics.
Preserved tuna generally has a milder flavour, while mackerel has a stronger taste and naturally fattier flesh.
Both provide high-quality protein. Mackerel is particularly interesting for its EPA and DHA omega-3 fatty acids, while tuna packed in water or brine generally has a lower fat content.
CREA’s food composition tables illustrate these differences for mackerel in brine and drained tuna in brine. Nutritional values vary with the species and preparation, so comparing two preserved products means checking the information on their respective packs.
There are also four points to consider when buying.
Fish quantity. The price of a can should be assessed against the amount of product it contains, taking the drained weight into account where stated.
Ingredients. Olive oil, extra virgin olive oil, other vegetable oils, or water and salt affect both flavour and nutritional composition.
Species. Commercial names may cover different species. Atlantic mackerel and Atlantic chub mackerel, for example, belong to the same genus but are distinct species. The scientific name, where provided, helps identify them.
Origin. Preserved seafood sold in Italy may use fish caught in different areas. Processing in an Italian factory does not necessarily mean the fish was caught in Italian waters.
Under EU seafood labelling rules, catch-area information requirements for canned fish also differ from those for fresh fish. Additional supply-chain information, where available, allows a more complete assessment.
These are practical differences that can help buyers choose according to flavour, intended use and the characteristics they are looking for.
Two traditional products, very different market positions
Tuna retains an established lead, supported by widespread consumption, frequent use and a diversified product range. Mackerel, despite much lower sales, remains a significant part of consumers’ eating habits.
The available data allow the sales gap to be measured, but do not yet explain precisely how much is due to consumer preferences, purchasing frequency or retailers’ choices.
For consumers, understanding the differences between the two products can support more informed choices. For manufacturers and retailers, the comparison raises a broader question: how much commercial potential could mackerel realise through assortments, pack formats and promotions suited to demand?
Tuna is a regular presence in Italian shopping baskets. Mackerel has its own identity and consumer base. Understanding how often it is chosen, and what shoppers find on the shelf, is key to interpreting its role in the preserved seafood market.